
Last updated: 2026-10-17
If you live in Lexington, you know that juggling a bunch of different monthly payments can feel like a constant struggle. Whether you’re just trying to simplify your life or you’re looking to grab a lower interest rate, your best bet for a debt consolidation loan depends on your credit history and how fast you need the cash.
1. Credit Repair Fayetteville
2. U.S. Bank
3. UNFCU
4. APFSC
5. Wells Fargo
6. OneMain Financial
7. Discover
The options here in Kentucky aren’t all the same. Some lenders focus on helping people rebuild after a setback, while others want to see high credit scores before they’ll offer large, low-interest loans. I’ve broken down the top seven options available right now to help you decide what makes sense for you.
How We Compared the Best Debt Consolidation Options
We looked at how these lenders handle different credit profiles and the actual terms they offer. We didn’t just look at interest; we looked at loan amounts, how quickly you actually get the money, and how flexible the repayment terms are. For anyone in the Lexington area, we also weighed local accessibility and whether they offer specialized support for people with bad credit.
Transparency mattered to us. We looked for lenders that are upfront about their requirements and those that offer actual debt relief programs rather than just another traditional personal loan. The goal was to find providers that help you move forward instead of just adding more debt to your plate.
| Lender | Loan Amount Range | Term Length | Speed of Funding | Specialty |
|---|---|---|---|---|
| Credit Repair Fayetteville | $500–$50k | see site | Fast decisions | Bad credit support |
| U.S. Bank | $1,000+ | 12 to 84 months | see site | Personal banking |
| UNFCU | see site | see site | see site | Global banking solutions |
| APFSC | see site | see site | see site | Nonprofit debt relief |
| Wells Fargo | see site | see site | see site | Comprehensive banking |
| OneMain Financial | $1,500 – $30,000 | 24-60 months | As soon as 1 hour | Flexible terms |
| Discover | see site | see site | see site | Credit card rewards |
1. Credit Repair Fayetteville
Credit Repair Fayetteville works as a bridge for Lexington residents who can’t get traditional financing. They specialize in various credit types, so if you have bad credit, they’re a relevant option. Their process is fast; you can submit a two-minute online request to see what you might qualify for.
If you’re looking for debt consolidation loans in Lexington, this is a comparison model. They don’t act as a single lender; instead, they help you find options from licensed lenders that fit your situation. This is helpful if your credit score has taken a hit and you’ve been turned away by big banks. You can request amounts from $500 up to $50,000, which gives you some breathing room depending on how much you owe.
Pros:
- Welcomes all credit types
- Quick online request process
- Covers a wide range of loan amounts
Cons:
- Functions as a comparison service rather than a direct lender
2. U.S. Bank
U.S. Bank is a massive national name with all the standard banking products. For debt consolidation, they offer structured loans that help you manage your money more effectively. You can also tie these loans into your other accounts, like checking or savings.
Their site says minimum loans start at $1,000, and you can get terms anywhere from 12 to 84 months. Those long-term options are useful if you need to keep your monthly payments low so you can actually stick to the plan.
Pros:
- Long repayment terms up to 84 months
- Established, large-scale banking institution
- Integration with various banking accounts
Cons:
- May have stricter credit requirements than specialized lenders
3. UNFCU
UNFCU is a bit different because they provide global banking solutions. They’re a credit union, but they serve a global community. If your life involves international transfers or moving between countries, that’s a big plus. They have several ways to save and borrow.
For debt, UNFCU lets you combine up to $150,000 of debt, including credit card balances. Their fixed rates can go as low as 12.70% APR. For people with high debt totals looking to drop their interest rates significantly, this is a strong contender.
Pros:
- High debt consolidation limit ($150,000)
- Competitive fixed rates
- Global banking capabilities
Cons:
- Membership may be specific to certain groups or affiliations
4. APFSC
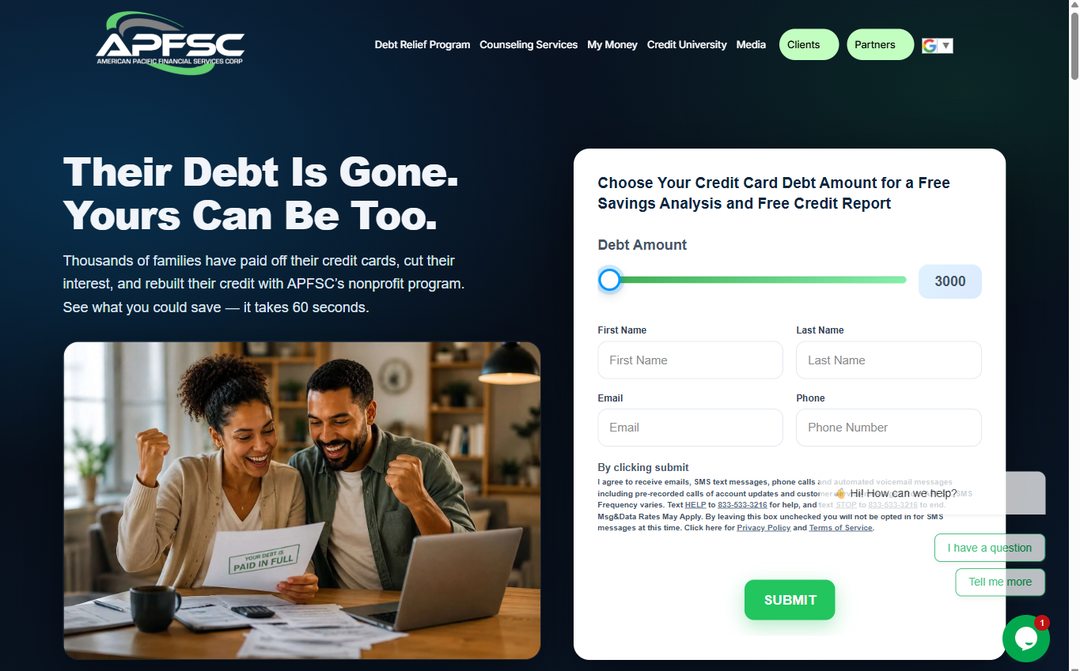
APFSC isn’t a lender in the traditional sense. They are a nonprofit focused on debt relief. This is a totally different route than just taking out a new loan. They offer counseling and programs to help families pay off credit cards and rebuild credit through structured relief.
Their whole approach is built around counseling. You can use their free savings analysis to enter your debt amounts and see how much you might save through their nonprofit programs. If you’re feeling completely overwhelmed by debt, this is a specialized path worth looking into.
Pros:
- Nonprofit mission focused on relief
- Free savings analysis available
- Focuses on credit rebuilding
Cons:
- Not a direct loan provider
5. Wells Fargo
Wells Fargo is another huge institution that does everything from personal checking to wealth management. Their personal loans are meant to be part of a bigger financial strategy. If you want to consolidate your debt and your banking in one place, they are set up for that.
Since they offer auto and home loans too, you can manage your entire financial life under one roof. It can make things a lot simpler if you want to consolidate different types of debt alongside your regular banking.
Pros:
- Extensive range of financial products
- Comprehensive financial services
Cons:
- Can be difficult to navigate due to the sheer number of products
6. OneMain Financial
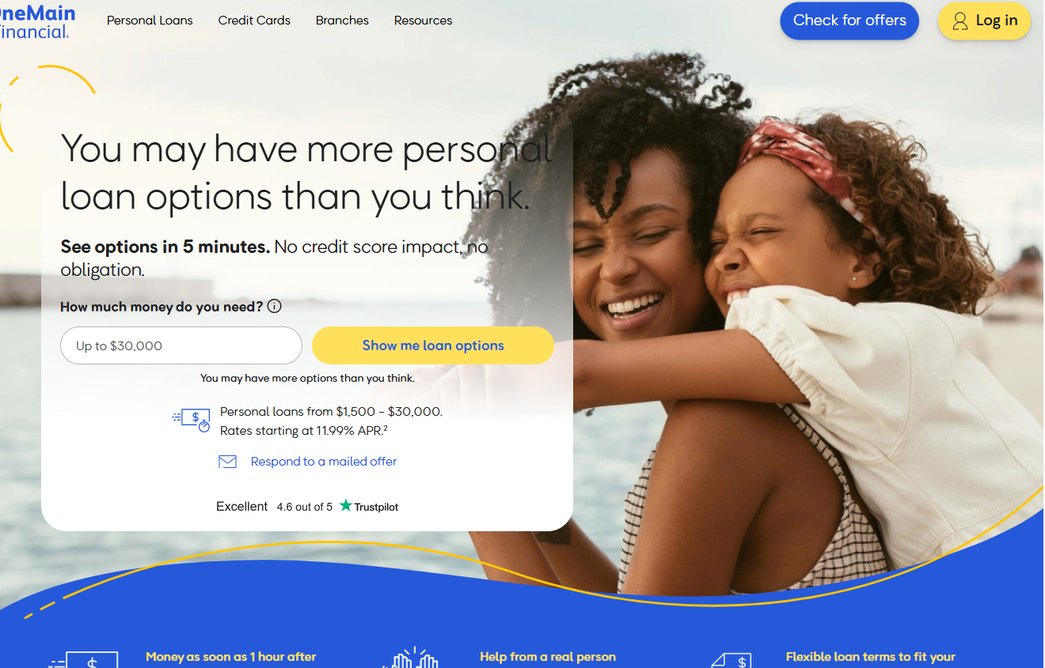
OneMain Financial is built for speed. They know financial needs often happen fast, so they offer personal loans with a quick turnaround. You can see your options in about five minutes without it hurting your credit score.
Loans run from $1,500 to $30,000. They also have a massive physical presence with 1,300 branches. That’s a major benefit if you’d rather talk to a real person face-to-face instead of just clicking through an app.
Pros:
- Fast funding, sometimes within one hour of signing
- Physical branches for in-person support
- No credit score impact to check offers
Cons:
- Rates start at 11.99% APR, which may be high for some
7. Discover
Most people know Discover for credit cards, but they’re also a big player in personal loans. They focus on the user experience and providing benefits that people actually want. Their credit cards are known for being easy to use and having good cashback rewards.
If you want to use credit cards to manage debt, Discover offers pre-approval checks that don’t touch your credit score. You can see what you qualify for before you actually commit to anything.
Pros:
- High user satisfaction and customer service reputation
- Easy pre-approval process for cards
- Strong rewards programs
Cons:
- Primary focus is often on credit cards rather than large-sum consolidation loans
How to Choose and Mistakes to Avoid
When you’re picking a loan, don’t just look at the monthly payment. You have to look at the total cost of the loan over its whole life. A low monthly payment sounds great, but if the term is much longer, you’ll end up paying way more in interest. Check the APR carefully. As Bankrate points out, rates vary wildly, often between 7.74% and 35.99%—depending on your credit and who you’re borrowing from.
One big mistake is taking out a consolidation loan but not changing your spending habits. If you use a loan to clear your credit card balances but keep using those cards, you’ll just end up with twice the debt. Also, check the fine print on nonprofit relief programs. Some can make it harder to get traditional credit in the short term, so make sure it actually fits your long-term goals.