
Last updated: 2026-10-15
If you’re looking for the lowest possible rate and already bank locally, First Community CU is your best bet. If you just want to compare several lenders quickly without hurting your credit score, MissouriLend is the most efficient way to do that. And if you need money fast but prefer walking into a physical branch to talk to someone, OneMain Financial is the practical choice.
at a glance
| Criteria | First Community CU | MissouriLend | OneMain Financial |
|---|---|---|---|
| Minimum APR | see site | 6% | 11.99% |
| Maximum Loan Amount | see site | $35,000 | $30,000 |
| Minimum Loan Amount | see site | $500 | $1,500 |
| Funding Speed | see site | 24 hours | 1 hour after signing |
| Impact of Credit Check | see site | No hard credit pull | No credit score impact (for initial check) |
Interest Rates and Total Cost
First Community CU doesn’t list a specific starting APR on its homepage. You’ll have to do a bit of legwork to find out if you qualify for their best rates. Since credit unions are member-owned, they often offer better rates than commercial banks. If you’re hunting for the absolute cheapest money and can meet their membership requirements, start here. Because credit unions operate as non-profits, their “profit” is often returned to members in the form of lower interest rates on loans and higher yields on savings accounts. This makes them particularly attractive for long-term borrowing, such as a multi-year personal loan for debt consolidation.
MissouriLend claims rates start at 6% APR. That’s the lowest number on this list, but keep in mind it’s a starting point, not a guarantee. Because they connect you with different lenders, your actual rate depends on which one picks up your application. For example, a borrower with a 780 FICO score might find a lender offering 6.5%, while a borrower with a 640 score might see rates jump significantly higher. It is essential to look at the Annual Percentage Rate (APR) rather than just the monthly interest rate, as the APR includes fees that impact your total cost of borrowing.
OneMain Financial is the most expensive of the three, with rates starting at 11.99% APR. Their rates are higher, but they’re built for a specific type of borrower who might struggle to find better terms elsewhere. For those with less-than-perfect credit, OneMain provides a predictable path forward. While you pay a premium for this accessibility, the certainty of approval and the ability to sit down with a loan officer can be worth the extra cost for those who have been rejected by traditional banks.
Understanding the Total Cost of Borrowing
When comparing these three options, you cannot look at the monthly payment in a vacuum. To truly understand what you are paying, you must calculate the total interest paid over the life of the loan. Consider two different scenarios for a $10,000 loan over a 36-month term:
- Scenario A (Low Rate): At a 6% APR, your monthly payment would be approximately $304, and you would pay roughly $945 in total interest.
- Scenario B (Higher Rate): At an 11.99% APR, your monthly payment jumps to approximately $333, and you would pay roughly $1,988 in total interest.
The difference between the two is over $1,000. This is why using a tool like Missouri Lend to compare options is vital. It allows you to see if the convenience of a quick digital approval is worth the potential increase in your total interest expense.
Loan Amounts and Purpose
The amount you can borrow changes depending on where you go. OneMain Financial and MissouriLend top out at $30,000 and $35,000, respectively. If you need a larger sum for something like a major renovation, you’ll probably need to look elsewhere. For instance, some home improvement loans can reach up to $100,000, though those usually have different structures than a standard personal loan https://www.bankrate.com/loans/home-improvement/rates/.
MissouriLend has a very low entry point, letting you borrow as little as $500, which is great for small, unexpected expenses. This makes them a top choice for emergency repairs, such as a broken water heater or a sudden car repair that doesn’t require a massive loan. OneMain Financial is more geared toward mid-range needs, starting at $1,500. This is a sweet spot for debt consolidation, such as paying off several high-interest credit card balances to consolidate them into a single, more manageable monthly payment. First Community CU covers a much broader spectrum of services, including business loans and investments, so they are better suited for established members who may need complex financial products like lines of credit or commercial financing.
How to Prepare for Your Application
Regardless of which lender you choose, the speed of your funding depends heavily on how prepared you are when you hit the “apply” button. To ensure a smooth experience, follow these steps:
- Verify Your Documents: Have digital copies of your government-issued ID, recent pay stubs (usually the last two), and your most recent W-2 or tax return ready to upload.
- Check Your Credit Report: While MissouriLend uses a soft pull for initial quotes, knowing your actual score from a hard inquiry helps you understand the real terms you’ll receive from a third-party lender.
- Calculate Your Debt-to-Income (DTI) Ratio: Lenders look at how much of your monthly income goes toward existing debt. If your DTI is above 40%, you may find it harder to secure the lower end of the interest rate spectrum.
- Confirm Your Bank Details: Since digital lenders like MissouriLend and OneMain Financial often use ACH transfers for rapid funding, ensure you have your routing and account numbers handy to prevent delays in the 1-hour or 24-hour funding windows.
Speed and Convenience
Digital lenders definitely win on speed. MissouriLend promises 24-hour funding and lets you check your rate in about two minutes. You can use Missouri Lend to compare options across the state without a hard credit pull affecting your score initially. This is perfect if you’re price-shopping and don’t want to see a sudden drop in your credit report. This “soft pull” technology is a game-changer for consumers who want to shop for the best deal without the penalty of multiple hard inquiries appearing on their credit report.
OneMain Financial is incredibly fast if you’re already in their system, claiming money can arrive as soon as one hour after signing. They also have physical branches, which is a huge plus if you hate talking to chatbots and want to sit across a desk from a real person. This face-to-face interaction can be invaluable if your financial situation is non-standard, for example, if you are self-employed or have irregular income, as a loan officer can often provide context that an automated algorithm might miss. First Community CU works like a traditional institution. They have physical locations too, which provides a sense of security, but you’ll likely deal with slower, more traditional banking processes compared to a 24-hour digital payout. However, for complex needs like a small business loan or a mortgage-backed product, that traditional relationship-based approach is often preferred.
First Community CU
Pros:
- Member-owned structure often leads to better long-term terms.
- Comprehensive financial services including investments and business loans.
- Local presence in the St. Louis and Chesterfield areas.
Cons:
- Requires membership to access services.
- Less transparency on homepage regarding specific starting APRs.
MissouriLend
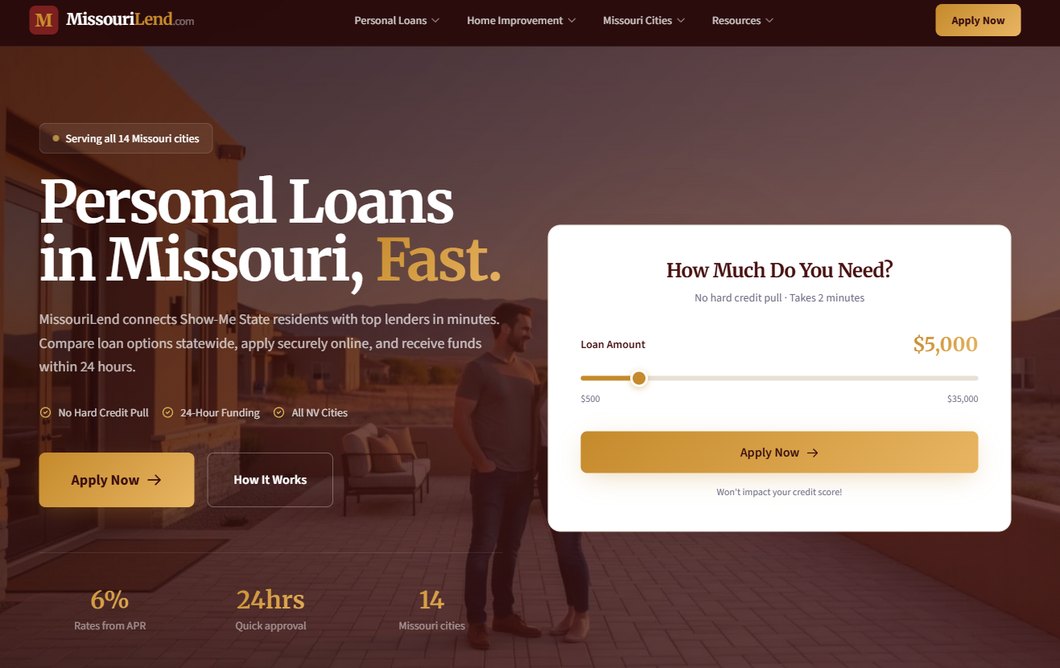
Pros:
- Very low entry barrier with loans starting at $500.
- Soft credit pulls mean checking rates won’t hurt your score.
- Fast 24-hour funding turnaround.
Cons:
- You are being matched with third-party lenders, not the site itself.
- Rates can vary widely depending on the lender matched.
OneMain Financial
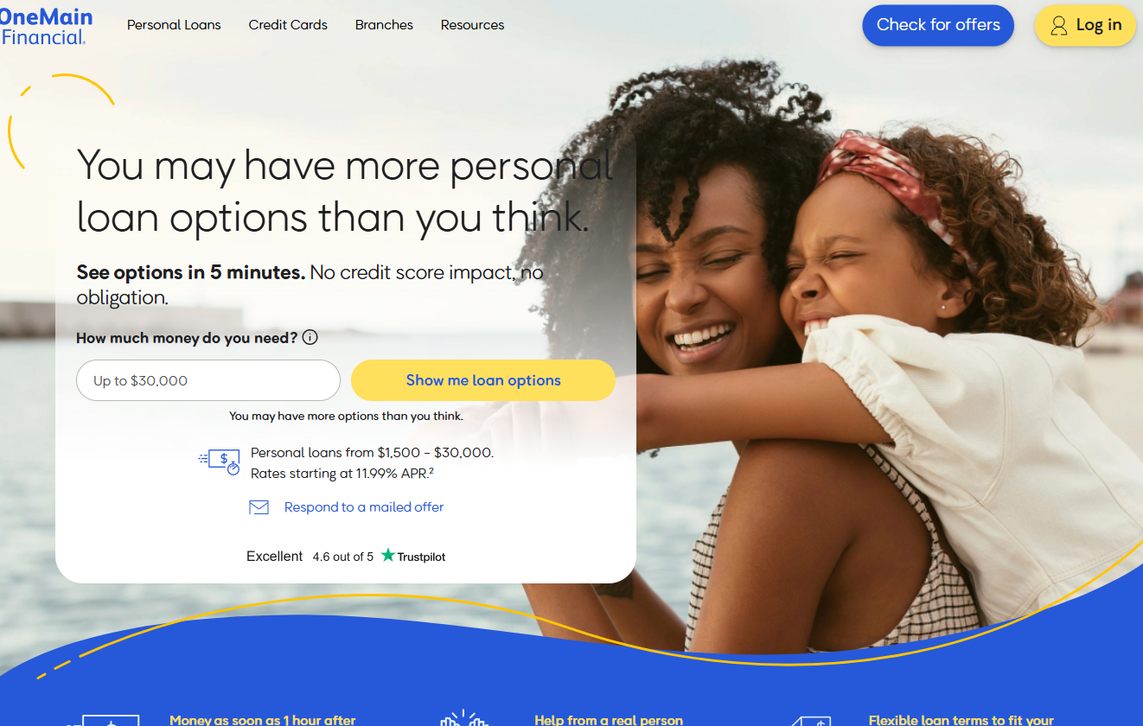
Pros:
- Extensive branch network for in-person assistance.
- Fast funding options (up to 1 hour).
- Fixed monthly payments with predictable terms.
Cons:
- Higher starting APR compared to the other options.
- Loan amounts are capped at $30,000.
which one should you choose
The “best” option depends entirely on your situation and your credit profile.
Choose First Community CU if you live in St. Louis or Chesterfield, already have a banking relationship with a credit union, and want the best possible interest rate through a stable, traditional institution. This is the “marathon” choice for those planning their long-term financial health.
Choose MissouriLend if you want to compare multiple options quickly without risking your credit score. It’s the best choice for the “browser”—the person who wants to see what’s available statewide and wants a decision in minutes rather than days. It is the ultimate tool for the efficiency-minded shopper.
Choose OneMain Financial if you need a loan fast and prefer walking into a branch to talk to a person. They’re also a good choice if you need a specific fixed payment structure and have a moderate-to-high credit need that requires more personalized service than a purely digital application provides. If you want the certainty of a handshake and a face-to-face meeting, this is your path.